Autumn turbulence

High oil prices, France’s debt burden, the US midterm elections and a host of questions surrounding artificial intelligence kept investors on their toes in October. Broad stock market indices were relatively steady, but some of the hottest stocks in the AI boom saw dramatic swings. Historically, stock markets have performed strongly in the months following US midterm elections with political uncertainty easing. We therefore maintain our overweight position in equities despite the autumn turbulence.

Sharp swings in technology stocks

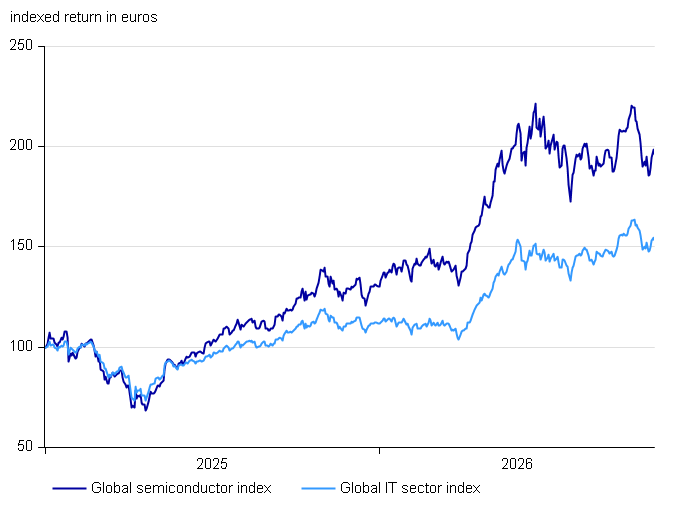
The global technology index reached an all-time high in early October, but has since fallen by around 10%. Familiar concerns, including fears of excessive investment and disappointing returns on that investment, have resurfaced. This has pushed share prices down, particularly in the semiconductor sector, where the outlook depends heavily on how quickly AI investment grows.
Sijoituskatsaus - IT ja puolijohde_ENG.png

The companies themselves remain very upbeat and expect the AI boom to continue to surge over the next few years. Korean memory chip manufacturer SK Hynix said its order book is full until 2029 and expected the chip shortage to last until 2030. Its rival Samsung, meanwhile, reported a third-quarter operating profit of USD 80 billion, a new world record for a technology company. Both companies’ share prices have dropped sharply from their peaks, and based on the current earnings forecasts for the next 12 months, their shares are trading at P/E ratios of around 3x. Such a low level will not persist, so either earnings forecasts will soon be cut substantially or share prices will rise significantly.

There have also been sharp share price movements outside the semiconductor sector. Higher interest rates and wider credit spreads have increased borrowing costs, creating challenges for the most heavily indebted companies. In recent weeks, markets have focused particularly on so-called neocloud companies, which build data centres and rent out their computing capacity to customers. These companies typically carry very high levels of debt. For example, the yield on CoreWeave’s bond maturing in five years has already risen to 15%. The AI boom still offers investors excellent opportunities, but not every company in the sector will emerge a winner.

US midterms draw closer

Investors are also weighing up the US midterm elections on 3 November. Alongside the rising cost of living, data centres have become a major election issue. Growing numbers of people are concerned about the impact of the data centre boom on water consumption, electricity prices and local landscapes. Reports of cyberattacks carried out by AI agents have also prompted many to question whether AI needs tighter regulation. Politicians, too, are having to take a stance on these issues, with critical voices considerably more common within the Democratic Party.

If the Democrats win a majority in both houses of Congress, they may very well seek to tighten AI regulation. However, the president has the power to veto legislation, so these efforts may not lead to changes. The elections for state governors held alongside the midterms will be particularly important for the data centre construction boom, as many states are considering restrictions on new projects. Investors are paying special attention to Texas, where the race for governor is shaping up to be tight and new projects have been temporarily put on hold.

With data centres attracting considerable media attention, the approaching midterms may have contributed to volatility in the technology sector. Historically, stock markets have often been somewhat subdued ahead of midterm elections, but have performed much more strongly in the months afterwards. We expect the AI boom to continue regardless of the election result. Ultimately however, the most important decisions about AI development are made by businesses, not politicians.

Central banks in wait-and-see mode

The European Central Bank (ECB) and the US Federal Reserve (Fed) left their policy rates unchanged at their late-October meetings. However, rate hikes could resume in December if energy prices remain high. Nordea’s economists expect the ECB to raise its policy rate twice more during this hiking cycle.

The price of Brent oil continued to rise in October, even though crude oil shipments from the Persian Gulf have returned to roughly their pre-crisis levels. However, oil supply still falls slightly short of demand and inventories are low, so prices are unlikely to fall significantly before a lasting peace is reached. The most severe supply constraints affect fuels such as diesel, as some refining capacity has been lost in both the Persian Gulf and Russia. Inflation risks therefore remain elevated: the longer energy prices stay high, the more likely businesses are to raise the prices of their end products.
Author

Hertta Alava

Hertta

Investment Strategist
Nordea Wealth Management

Economic growth remains strong

Despite higher interest rates and energy prices, the global economy has continued to grow steadily. In October, the International Monetary Fund (IMF) raised its global growth forecast by 0.1 percentage points

to 3.1%. The US economy is expected to grow by 2.3% both this year and next. AI investment has become so substantial that it now makes a significant contribution to overall economic growth. Investment bank Goldman Sachs estimates that AI investment will account for around 1.8% of US GDP this year and 2.5% next year. In comparison, investment reached around 2–5% of GDP in the peak years of previous major booms, with the highest levels recorded at the height of railway construction.

Europe’s AI boom is not yet as advanced as that of the US, but data centre construction is now gathering pace here too. Finland is also attracting a share of this investment. Google’s projects in particular are so large that their impact will show up in national economic growth figures. Overall, eurozone growth is likely to be around 1% this year. Encouragingly, the economy in Germany has finally picked up after three years of zero growth. The IMF forecasts German GDP growth of 1.3% this year driven by increasing investment in defence and infrastructure.

France has now replaced Germany as Europe’s economic weak spot. Concerns about the country’s debt resurfaced in October when its 10-year government bond yield rose to 5%. The gap relative to the equivalent German bond has already reached 1.5 percentage points, reflecting markets’ lack of confidence in the sustainability of France’s public finances. Government debt has risen to 120% of GDP, with the budget having run a deficit every year since the 1970s. An ageing population further clouds the longer-term outlook, as France has not built up pension funds to cover future payments. The country holds a presidential election next year, which is unlikely to make politicians more willing to cut spending.

Earnings growth is the key driver

Growth forecasts for corporate earnings have been upgraded substantially as the year has progressed. Third-quarter earnings have come in broadly as expected, increasing confidence in the forecast of more than 30% global earnings growth for the full year. The outlook for next year is also favourable, although earnings growth is expected to halve to around 15%. This largely reflects semiconductor companies’ triple-digit earnings growth slowing to more moderate levels. If earnings continue to grow as strongly as expected, share valuation multiples will quickly fall to very attractive levels. Strong earnings growth is therefore the main reason for our recommendation to maintain an overweight position in equities.

Emerging market equities, financials and IT remain overweight

We recommend maintaining an overweight position in emerging market equities, even though turbulence in semiconductor stocks has hit Korea – the second-largest country in the emerging markets index – particularly hard. October was turbulent also in the Brazilian market. Shares initially surged early in the month after right-wing candidate Flavio Bolsonaro won the most votes in the first round of the presidential election. However, investors were disappointed when left-wing candidate Lula da Silva won the second round, and share prices plunged back to where they had started. The congressional and state governor elections went better for the right, which could lead to tighter control of public spending despite the president’s tendency towards populism. Among Nordea's funds, a broadly diversified investment option for emerging-market equities is, for example, Nordea Emerging Market Equities Fund*.

In our sector recommendations, we have upgraded energy to neutral weight, as the conflict in the Middle East has lasted longer than we expected and it may take considerable time for the energy markets to return to balance. At the same time, we have downgraded industrials from overweight to neutral. IT and financials remain overweight. Growth prospects for the IT sector are still strong, while financials benefit from steady economic growth.

Nordea Emerging Market Equities A Growth*

  • The fund invests in emerging markets with a broad diversification.
  • Asian technology companies are key players in the global AI boom.
  • The increase in raw material prices benefits Latin America.
  • Growth is also driven by urbanization and the increasing wealth of the middle class.
  • The valuation level is attractive.

Read more

Bonds offer stability and returns

Bond yields remain at attractive levels, offering a compelling option for risk-averse investors. Credit spreads have widened slightly in recent months, but remain relatively low by historical standards. Concerns about individual companies’ debt have therefore not triggered broader worries across the corporate bond market. We are keeping all bond segments at neutral weight. Among Nordea's funds, a diversified option for investing in fixed-income markets is, for example, Nordea Savings Fixed Income*. 

Nordea Savings Fixed Income*

  • You gain access to a fund actively managed by experts that is diversified across a broad range of fixed-income instruments, including eurozone government bonds, corporate bonds (both investment grade and high yield), covered bonds and money market instruments.
  • The fund adheres to Nordea’s Responsible Investment Policy.

Read more

Asset class recommendations

November 2026

Asset classes

Asset classesRecommendationRelative to neutral weight (% points)
EquitiesOverweight+5
BondsNeutral weight
0
Money marketUnderweight-5

Equity markets

Equity marketsRecommendationRelative to neutral weight (% points)Recommended allocation
North AmericaNeutral weight
050%
Western Europe Underweight-510%
FinlandNeutral weight015%
JapanNeutral weight05%
Emerging marketsOverweight520%

Bond markets

Bond
markets

RecommendationRelative to neutral weight (% points)Recommended allocation
Government bondsNeutral weight030%
Corporate bondsNeutral weight050%
High-yield bondsNeutral weight020%
Emerging market bondsNeutral weight00%

Returns by asset class

Vakiograafit - Osakkeet ja korot_enkku.png

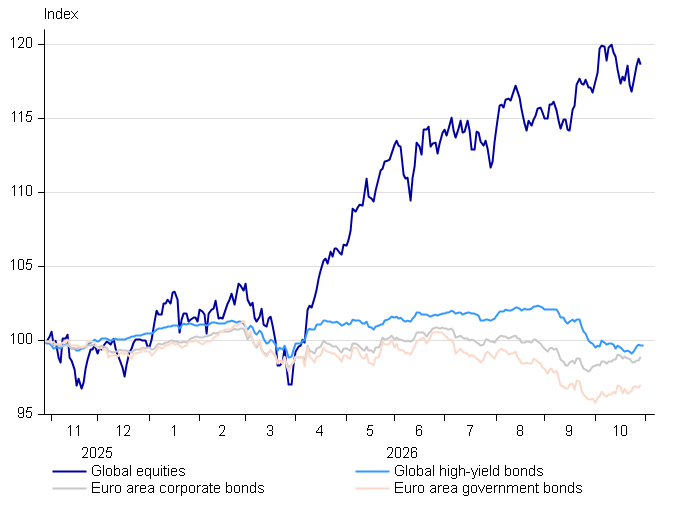
Asset class returns for the past 12 months: Global equities 18,7 %, Global high yield bonds 0,3 %, Eurozone corporate bonds -1,1 %, Eurozone government bonds -3,0 %.

Returns by equity region

Vakiograafit - Osakealueet_enkku.png

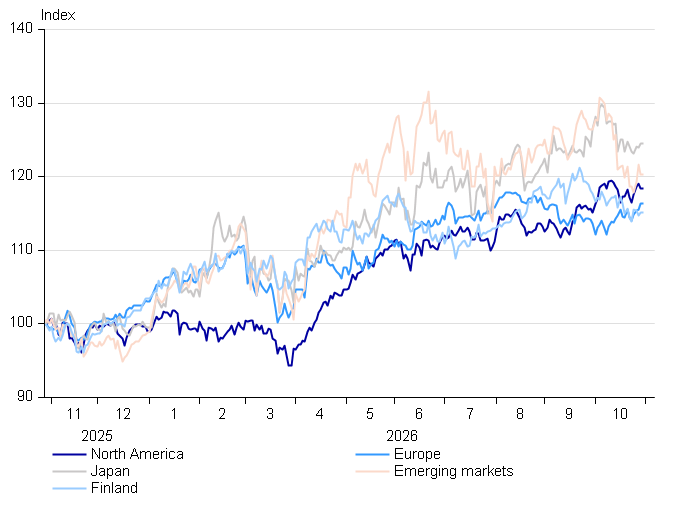
Asset class returns for the past 12 months: North America 18,4 %, Europe 16,4 %, Japan 24,6 %, Emerging markets 20,3 %, Finland 15,1 %.

Editorial

Responsible editor
Antti Saari, Wealth Management, Nordea Bank Abp
antti.saari@nordea.com

Content production
Hertta Alava, Ville Korhonen, Antti Saari, Teemu Mäkelä

Registered address and domicile
Satamaradankatu 5, Helsinki FI-00020 NORDEA
Business ID 2858394-9

E-mail

Disclaimer

* Important information

Investment services are provided by Nordea Bank Abp. The issuer of the products described in this message is Nordea Funds Oy. The information provided in this message is intended as general product information only. This information is not an exhaustive description of the products or the risks related to them and does not constitute investment advice or recommendations. Remember that investing always involves risks. The return on your investment may fluctuate, and you may lose some or all of your capital. Past performance is not a guarantee of future results. Before making any investment decisions, you should read the relevant prospectus and key investor information documents for more details about the investment product.

This message contains marketing content.